GaN Power Device Market Size and Forecast 2026 to 2035
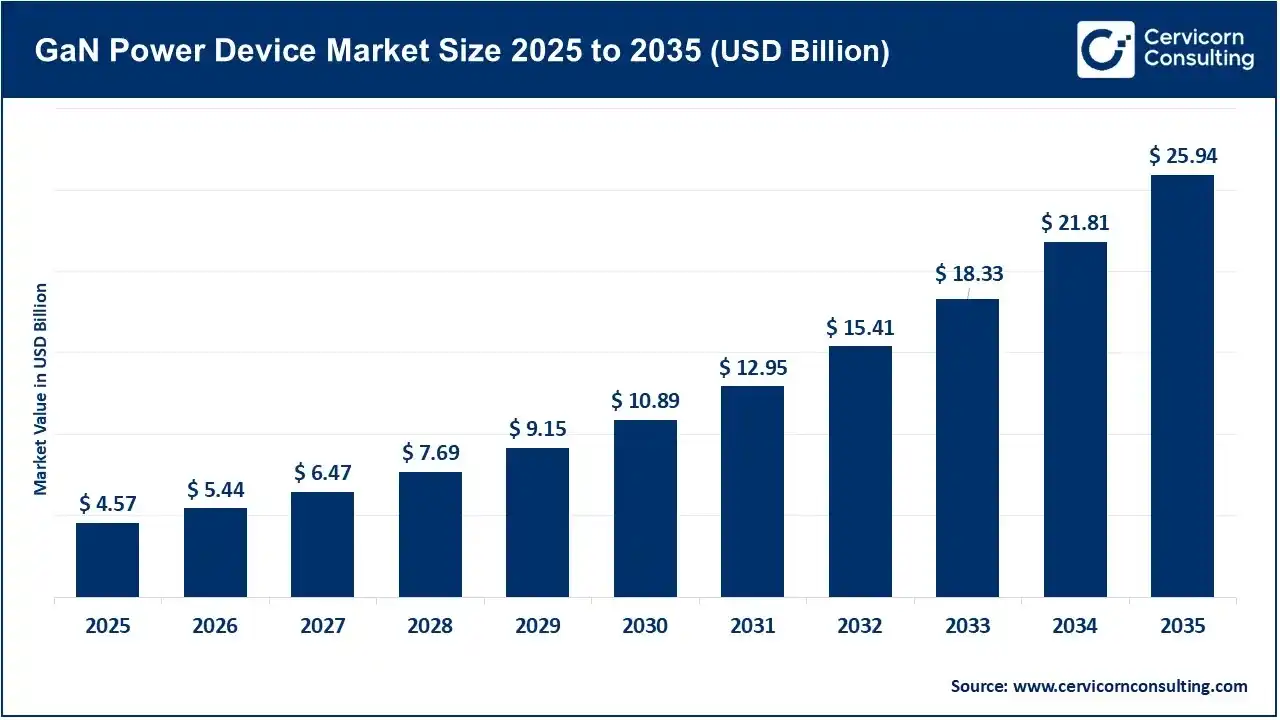
The global GaN power device market size was valued at USD 4.57 billion in 2025 and is projected to grow from USD 5.44 billion in 2026 to nearly USD 25.94 billion by 2035, registering a CAGR of 19% over the forecast period 2026 to 2035. The market is growing due to the increasing demand for energy-efficient, high-performance power electronics.
Key Statistics
- Base Year Market Size (2025): $4.57 Billion
- Current Year Market Size (2026): $5.44 Billion
- Estimated Year Market Size (2035): $25.94 Billion
- Forecast Period CAGR (2026-2035): 19%
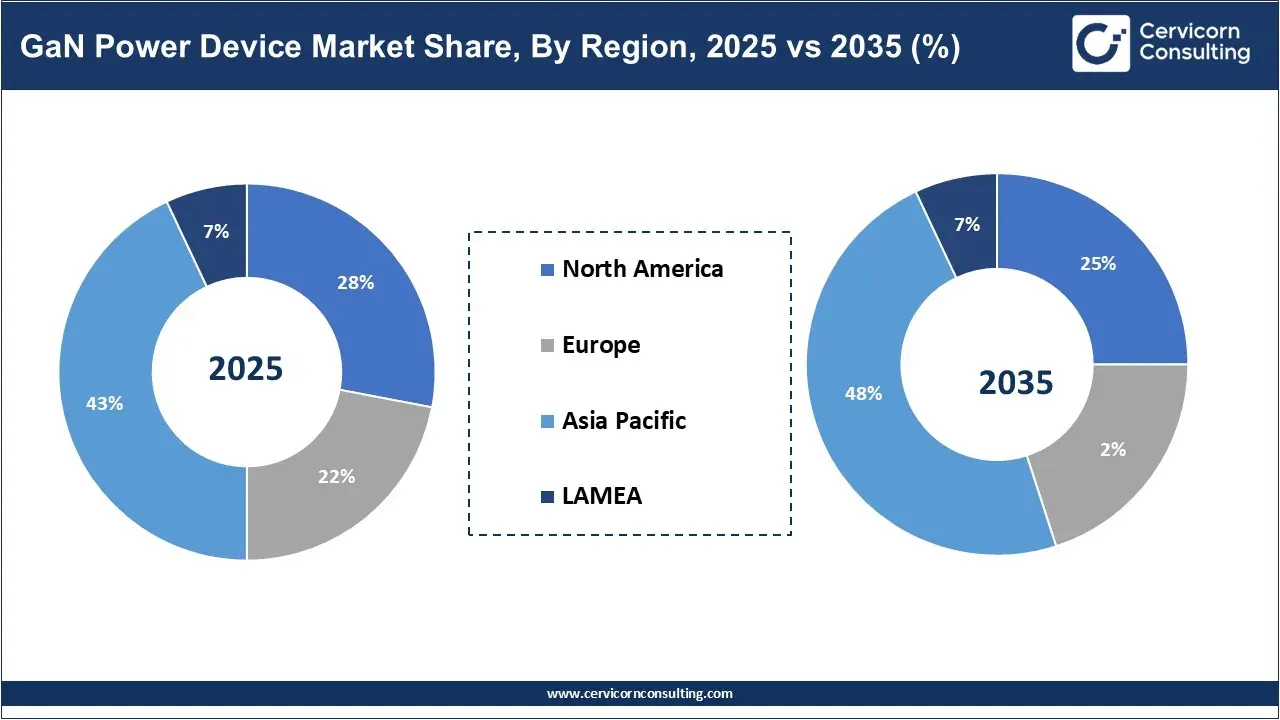
- Leading Region: Asia-Pacific (43% revenue share)
Report Highlights
- By region, Asia Pacific held the leading position in the market in 2025 (revenue share 43%), supported by its strong electronics manufacturing base, semiconductor production, and growing demand for energy-efficient power technologies.
- By region, North America is expected to expand rapidly, driven by rising investments in AI data centers, electric mobility, and advanced semiconductor technologies.
- By device type, GaN power discrete devices led the market in 2025 (revenue share 42%), owing to their wide adoption in chargers, adapters, power supplies, and other power conversion systems.
- By device type, GaN power ICs are expected to witness rapid growth, supported by the increasing need for integrated devices that offer compact designs and efficient power management.
- By voltage range, the 200–600 V segment accounted for the leading position in 2025 (revenue share 57%), due to its suitability for chargers, consumer electronics, power supplies, and other mainstream applications.
- By voltage range, the 900–1,200 V segment is expected to grow rapidly, supported by increasing demand for higher-voltage power solutions in EVs, data centers, and industrial systems.
- By substrate/technology, GaN-on-silicon led the market in 2025 (revenue share 68%), benefiting from established manufacturing processes, scalability, and broad commercial use.
- By substrate/technology, vertical GaN is expected to experience rapid growth, driven by its potential for high-voltage, high-power, and high-density power applications.
- By application, power supply systems held the leading position in 2025, supported by the growing need for smaller, more efficient, and high-performance power conversion solutions.
- By application, EV on-board chargers are expected to grow rapidly, driven by increasing electric vehicle adoption and the demand for lightweight and efficient charging systems.
- By end-use industry, consumer electronics led the market in 2025, supported by increasing GaN adoption in smartphones, laptops, chargers, gaming devices, and other electronic products.
- By end-use industry, automotive and transportation are expected to grow rapidly, driven by vehicle electrification and the increasing use of advanced power electronics in electric vehicles.
- By power rating, the 100–500 W segment dominated the market in 2025 (revenue share 35%), supported by strong demand for consumer chargers, adapters, and compact power supply products.
- By power rating, the 1–10 kW segment is expected to grow rapidly, driven by increasing demand for higher-power solutions in EVs, data centers, renewable energy systems, and industrial applications.
What Is Driving the Growth of the GaN Power Device Market?
The GaN power device market is growing because consumer electronics, electric vehicles (EV), data centers, telecommunications, and industrial applications all have a growing need for high-performance, energy-efficient power electronics. GaN power devices are becoming more and more in demand as fast chargers, small power supplies, renewable energy systems, and sophisticated power management technologies become more widely used. In comparison to traditional silicon-based devices, their capacity to provide faster switching speeds, reduced power losses, smaller system sizes, and enhanced energy efficiency is further bolstering market expansion.
In February 2026, Infineon Technologies introduced its CoolGaN Drive HB 600 V G5 product family, integrating GaN switches and gate drivers into compact half-bridge solutions. The new devices are designed to support higher switching frequencies, lower power losses, greater power density, and more compact power electronics, supporting the growing adoption of GaN technology across consumer and industrial applications.
Major Trends
- Rising use in fast chargers: GaN is becoming more popular in fast-charging devices because it supports smaller, lighter, and more efficient chargers.
- Growing demand from data centers: Increasing power consumption from AI and data centers is driving the need for efficient GaN-based power solutions.
- Increasing use in electric vehicles: GaN devices are finding new applications in EV charging systems and other vehicle power electronics.
- Expansion beyond consumer electronics: GaN adoption is moving into industrial equipment, telecommunications, renewable energy, and automotive applications.
- Development of higher-power devices: Manufacturers are improving GaN technology to support higher voltage and power requirements.
- Focus on integrated solutions: Companies are developing integrated GaN devices that combine multiple functions to reduce system size and improve efficiency.
- Growing manufacturing capacity: Investments in GaN production are helping manufacturers increase supply and support broader market adoption.
Market Dynamics
Growth Driver
Rising Demand for Energy-Efficient Power Electronics
The market for GaN power devices is propelled by the increasing demand for high-performance, compact, and efficient power electronics. GaN devices are appropriate for fast chargers, data centers, electric vehicles, telecommunications, and industrial equipment because they have higher power density, faster switching, and lower energy losses than traditional silicon devices. The market is expanding as a result of the growing emphasis on lowering energy usage and enhancing electronic system performance.
In February 2026, Navitas Semiconductor announced new GaN power solutions designed for AI data centers, including 650V GaN technology and high-power platforms. The development reflects the increasing use of GaN technology in high-efficiency power infrastructure for AI and data center applications.
Restraint
High Manufacturing Costs and Technical Challenges
The comparatively high cost and complexity of producing GaN-based devices limits the market for GaN power devices. Development and manufacturing costs can be raised by sophisticated production techniques, specialized machinery, packaging specifications, and testing protocols. Adoption may also be more difficult for certain manufacturers due to issues with thermal control, dependability, and integration with current power systems.
In November 2025, GlobalFoundries announced a technology licensing agreement with TSMC for 650V and 80V GaN technology. The agreement highlights the importance of specialized GaN technology and manufacturing capabilities for expanding GaN applications across high-power markets.
Key Opportunity
Expansion of GaN into High-Power Applications
The increasing use of AI data centers, electric cars, renewable energy systems, industrial equipment, and sophisticated charging infrastructure presents opportunities for the GaN power device market. Businesses are being motivated to create higher-power GaN devices by the growing need for more compact and effective power conversion systems. GaN technology's market potential can be increased by extending its use beyond consumer electronics.
In February 2026, Navitas Semiconductor introduced new 650V GaN solutions aimed at AI data center applications and highlighted an all-GaN 10 kW power platform for high-efficiency power conversion. These developments demonstrate the expansion of GaN technology toward higher-power applications.
Regional Analysis
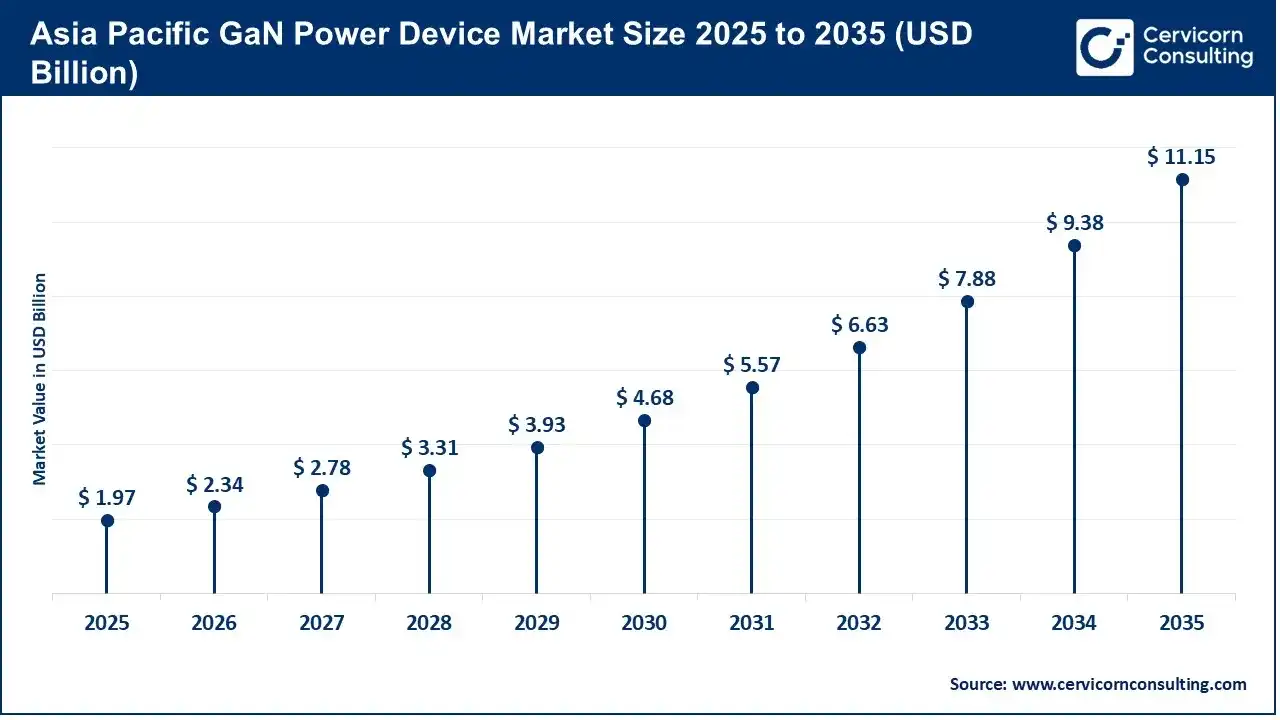
The Asia-Pacific GaN power device market size was valued at USD 1.97 billion in 2025 and is projected to surpass USD 11.15 billion by 2035. Asia Pacific dominated the market in 2025, backed by a sizable base of semiconductor and electronics manufacturers and a robust market for consumer electronics, telecommunications, electric cars, and cutting-edge power systems. The development of regional markets is further supported by the existence of significant semiconductor and electronics manufacturing facilities in China, Japan, South Korea, and Taiwan. GaN device production and downstream integration are made possible by strong manufacturing capabilities. Regional demand is also being supported by growing investments in electric mobility and semiconductor infrastructure.
The North America GaN power device market size was estimated at USD 1.28 billion in 2025 and is expected to hit USD 7.26 billion by 2035. North America is growing rapidly in the market, propelled by rising investments in semiconductor technologies, advanced power infrastructure, electric vehicles, and AI data centers. The market is expanding due to rising demand for high-efficiency power conversion and ongoing GaN technology development by local businesses. The need for effective power delivery and thermal management solutions is growing due to the quick development of AI computing. The region's growth prospects are also aided by government support for domestic semiconductor manufacturing and technological advancement.
Segmental Analysis
Device Type Analysis
GaN power discrete devices dominated the GaN power device market due to their extensive use in power conversion applications, such as industrial electronics, chargers, adapters, and power supplies. Because of their compact designs, high switching speeds, and reduced power losses, these devices are appropriate for applications where power density and energy efficiency are crucial. Their market position is sustained by their well-established commercial availability and expanding adoption in consumer electronics and industrial systems. GaN power discrete devices are becoming more popular due to the growing need for more compact and effective power electronics.
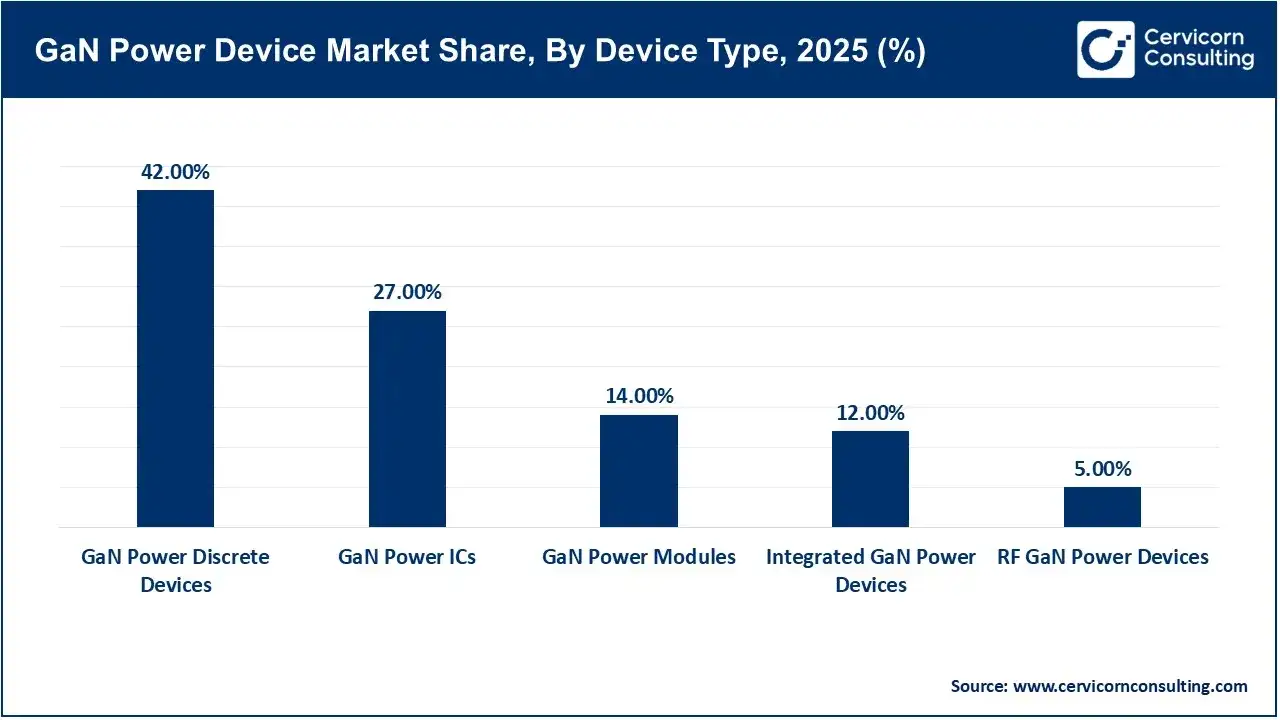
GaN power ICs are expected to be the fastest-growing segment, motivated by the growing need for compact, highly integrated power solutions. These devices help lower the number of components, system size, and power losses by combining GaN power technology with control and driver functions. GaN power ICs are seeing increased use in consumer electronics, data center power systems, fast chargers, and other high-efficiency applications. Segment growth is anticipated to be further supported by ongoing developments in power management and integration.
Voltage Range Analysis
The 200–600 V segment dominated the GaN power device market because it can be used with a wide range of devices, including power conversion systems, chargers, industrial equipment, and consumer electronics. A balance between efficiency, switching performance, and application flexibility is offered by devices operating in this voltage range. The market is still being strengthened by their well-established use in GaN products that are sold commercially and the rising demand for high-efficiency power supplies.
GaN Power Device Market Share, By Voltage Range, 2025 (%)
| Voltage Range |
Revenue Share, 2025 (%) |
| Below 200 V |
18% |
| 200–600 V |
57% |
| 600–900 V |
18% |
| 900–1,200 V |
5% |
| Above 1,200 V |
2% |
The 900–1,200 V segment is growing rapidly in the market, driven by the growing need for higher-voltage power conversion in data center infrastructure, industrial equipment, renewable energy systems, and electric vehicles. Higher-power applications are becoming possible thanks to developments in GaN materials, device structures, and manufacturing techniques. Manufacturers are putting more effort into enhancing voltage handling and dependability for harsh operating conditions. It is anticipated that this market will have more opportunities as electrification and high-power computing infrastructure grow.
Substrate / Technology Analysis
GaN-on-silicon dominated the GaN power device market in 2025, backed by its scalable production capabilities and compatibility with well-known semiconductor manufacturing processes. Widespread use in chargers, adapters, consumer electronics, and other power conversion applications has been prompted by its suitability for economical manufacturing. Manufacturers are also able to scale production more effectively thanks to the availability of the current silicon manufacturing infrastructure. GaN-on-silicon device performance is continuing to improve, which is encouraging its use in a wider variety of applications.
GaN Power Device Market Share, By Substrate, 2025 (%)
| Substrate |
Revenue Share, 2025 (%) |
| GaN-on-Silicon |
68% |
| GaN-on-Silicon Carbide |
11% |
| GaN-on-Sapphire |
4% |
| GaN-on-GaN |
5% |
| GaN-on-QST |
6% |
| Vertical GaN |
3% |
| Others |
3% |
Vertical GaN is growing rapidly in the market, motivated by its capacity to provide better electrical performance, increased power density, and higher voltage capability. Opportunities for broader adoption are being created by the growing development of vertical GaN devices for high-power applications such as data centers, electric vehicles, and industrial equipment. New device architectures created for demanding power conversion requirements can be supported by the technology. It is anticipated that ongoing research into manufacturing procedures and device dependability will hasten its commercialization.
Application Analysis
Power supply systems dominated the GaN power device market in 2025, supported by the growing need for small and effective power conversion solutions in data centers, consumer electronics, telecommunications, and industrial equipment. GaN devices are appropriate for contemporary power supply designs because they allow for high-frequency switching, reduced energy losses, and enhanced power density. The demand for sophisticated power supply technologies is rising due to the increasing use of energy-efficient electronic systems. GaN device integration is also being supported by the need for lighter and more compact power systems.
EV on-board chargers are growing rapidly in the market, driven by the growing popularity of electric cars and the need for charging systems that are lighter, more compact, and more effective. Manufacturers can create compact onboard charging solutions for electric vehicles thanks to GaN technology's ability to support higher switching frequencies and improved power density. Power electronics that can reduce system weight and size while increasing vehicle efficiency are becoming more and more sought after by automakers. More opportunities for GaN-based charging technologies are anticipated as infrastructure for electric mobility expands.
End-Use Industry Analysis
Consumer electronics dominated the GaN power device market in 2025, backed by the extensive use of GaN technology in gaming consoles, laptops, chargers, adapters, smartphones, and other electronics. The use of GaN devices in this sector is still supported by rising consumer demand for quick charging, more compact power accessories, and increased energy efficiency. Compact power solutions are becoming more and more necessary as the number of connected and portable electronic devices rises. In order to enhance charging performance and energy efficiency, manufacturers are also incorporating GaN technology into consumer electronics with higher power.
Automotive and transportation are growing rapidly, fueled by the advancement of sophisticated automotive power electronics and the growing electrification of vehicles. GaN technology is finding new applications in electric and hybrid vehicles due to the growing need for effective auxiliary power systems, power converters, and onboard chargers. Manufacturers are being motivated to investigate GaN-based solutions due to the need to decrease charging time, system weight, and power losses. It is anticipated that ongoing advancements in automotive semiconductor and electric mobility technologies will facilitate additional market growth.
Power Rating Analysis
The 100–500 W segment dominated the GaN power device market in 2025, backed by a robust market for consumer electronics, adapters, chargers, and small power supply systems. Applications needing a balance between high efficiency, small size, and quick switching performance are well suited for this power range. High-power charging accessories are becoming more and more popular, which is driving demand in this range. Its compatibility with a broad range of electronic devices also encourages ongoing commercial adoption.
GaN Power Device Market Share, By Power Rating, 2025 (%)
| Power Rating |
Revenue Share, 2025 (%) |
| Below 100 W |
32% |
| 100–500 W |
35% |
| 500 W–1 kW |
15% |
| 1–10 kW |
13% |
| Above 10 kW |
5% |
The 1–10 kW segment is growing rapidly, driven by the growing need for higher-power systems in data centers, industrial equipment, renewable energy, and electric vehicles. The technology's expansion into these applications is being aided by improvements in GaN device performance and power-handling capabilities. Manufacturers are being encouraged to create GaN solutions for higher power levels due to the growing need for high-density and energy-efficient power conversion. Additional growth prospects are anticipated due to the growing electrification of transportation and industrial infrastructure.
Government Initiatives
- In April 2025, the Government of India continued its support for semiconductor manufacturing through the Semicon India Programme, which provides fiscal support for compound semiconductor fabs, discrete semiconductor fabs, and semiconductor packaging facilities. These measures can support the development of domestic GaN manufacturing capabilities and strengthen the broader power semiconductor ecosystem in India.
- In February 2026, the Government of India announced further progress under the Semicon India Programme with 10 approved semiconductor projects covering fabrication, packaging, and other semiconductor technologies. The initiative aims to build a complete domestic semiconductor ecosystem covering design, fabrication, assembly, testing, and packaging, which can support future adoption of advanced power semiconductor technologies.
- In May 2026, the Union Cabinet approved two additional semiconductor manufacturing projects, including India's first commercial Mini/Micro-LED display facility based on GaN technology. The project includes compound semiconductor fabrication and GaN foundry services, strengthening India's domestic GaN manufacturing capabilities and supporting applications across displays and advanced electronics.
- In July 2026, the Union Cabinet approved Semicon 2.0 with a focus on strengthening India's semiconductor design and manufacturing ecosystem. The programme includes support for compound semiconductor fabs, advanced packaging, research and development, semiconductor materials, and talent development. These measures can further strengthen the infrastructure required for advanced power semiconductor technologies, including GaN.
Recent Developments
- In May 2026, Cyient Semiconductors launched seven GaN power devices for the Indian market using Navitas Semiconductor’s GaN technology. The portfolio covers applications including AI data centers, telecommunications, consumer fast charging, industrial power systems, and e-mobility. The launch also supports the development of India’s domestic GaN power semiconductor ecosystem.
- In June 2026, onsemi introduced its GaNEXUS gallium nitride power portfolio, covering devices from 40 V to 650 V. The new portfolio is designed to improve power density, efficiency, and thermal performance across AI data centers, industrial automation, robotics, and energy infrastructure applications.
- In August 2026, Ampleon expanded its GaN power portfolio with an 800 W GaN-on-SiC HEMT for the 902–928 MHz ISM band. The new device is designed for high-power RF applications and reflects the continued expansion of GaN technology into high-power communication and industrial systems.
Key Companies
Segments Covered
By Device Type
- GaN Power Discrete Devices
- GaN Power ICs
- GaN Power Modules
- Integrated GaN Power Devices
- RF GaN Power Devices
By Voltage Range
- Below 200 V
- 200–600 V
- 600–900 V
- 900–1,200 V
- Above 1,200 V
By Substrate / Technology
- GaN-on-Silicon
- GaN-on-Silicon Carbide
- GaN-on-Sapphire
- GaN-on-GaN
- GaN-on-QST
- Vertical GaN
- Other GaN Technologies
By Application
- Power Supply Systems
- Power Adapters & Fast Chargers
- Power Drives
- DC-DC Converters
- AC-DC Converters
- Inverters
- EV On-Board Chargers
- Solar Microinverters
- Data Center Power Systems
- Wireless Charging
- RF Power Systems
- Other Applications
By End-Use Industry
- Consumer Electronics
- Telecommunications
- Automotive & Transportation
- Data Centers & IT
- Renewable Energy
- Industrial
- Aerospace & Defense
- Healthcare
- Energy & Utilities
- Others
By Power Rating
- Below 100 W
- 100–500 W
- 500 W–1 kW
- 1–10 kW
- Above 10 kW
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
