
Content
Clinical Trial Supplies Market Projected to Reach USD 12.93 Billion by 2035


Clinical Trial Supplies Market Insights
The global clinical trial supplies market size accounted for USD 6.20 billion in 2026 and is expected to grow at USD 12.93 billion by 2035, growing at a CAGR of 8.5% during the forecast period of 2026 to 2035. North America registered dominance in the market in 2026 because of its well-established clinical research infrastructure center, whereas Asia-Pacific is anticipated to grow rapidly due to a surge in clinical trial solutions and affordability across running clinical trials.
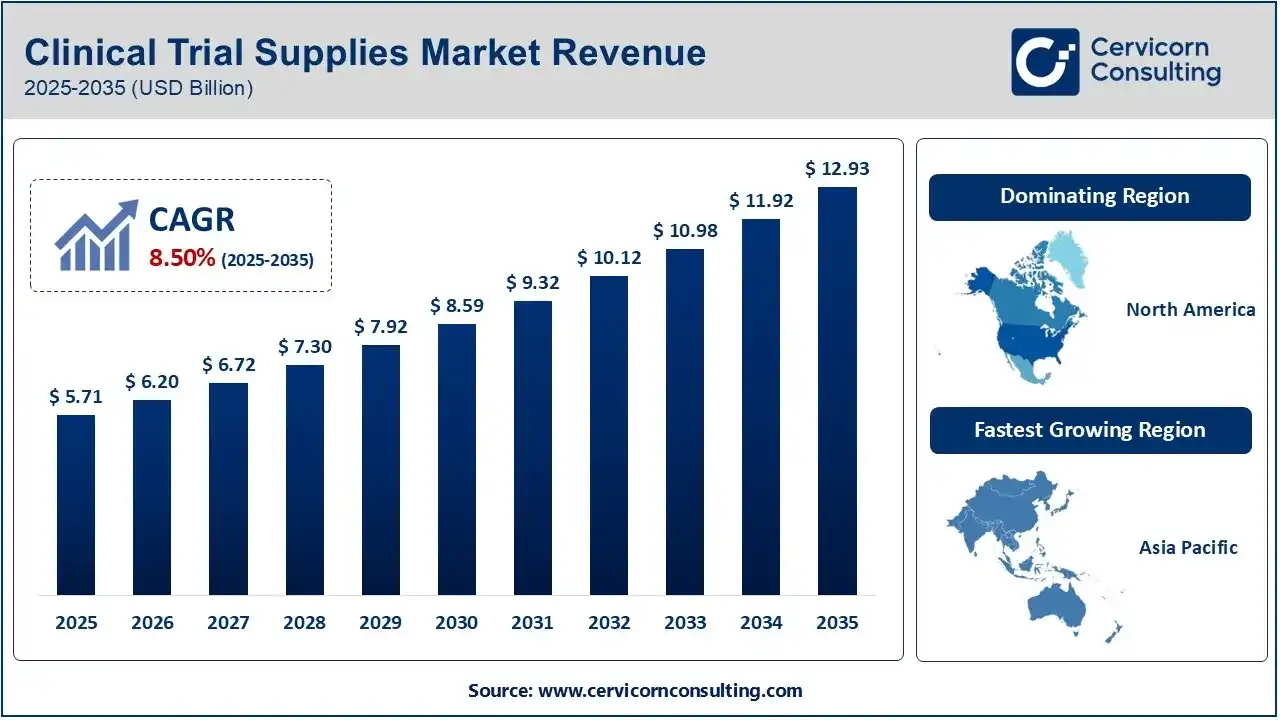
Clinical Trial Supplies Market Outlook
The overall market covers execution of planning, sourcing, packaging, labelling, storage, distribution, and handling of investigational drugs and study-related materials for clinical research. The market progression is mainly fueled by a rise in global trials, including multinational and multi-regional trials, to boost accessibility for various patient populations. This leads to a need for complex, expansive logistics, import or export permits, etc. The worldwide growing diverse chronic concerns drive the demand for advanced biologics, cell and gene therapies, and personalized medicines, requiring unique prediction, rigorous temperature-controlled cold chains and defined shelf-life management.
With a key emphasis on AI and predictive analytics, the market is promoting decentralized clinical trials (DCTs), i.e. direct-to-patient (DtP) delivery, home nursing visits, and digital tracking to replace traditional offerings.
Major AI Roles
In 2026, AI has been bolstering as most wanted or revolutionizing approach across the globe, while clinical trial supply (CTS) is widely leveraging machine learning models to support linked datasets. This will enable analysts to coordinate drug and device supply exactly with real analysis demand. Furthermore, AI algorithms have expanded digital twins and real-time simulations to assess faster-than-expected patient recruitment surges, domestic manufacturing challenges, or cold-chain disruptions. On the other hand, several regulatory agencies, including the FDA and EU regulators, are broadly expecting full data provenance, explainable logic, and algorithmic visibility instead of opaque AI results.
Regional Overview
North America Led the Market in 2025
The clinical trial supplies market in North America captured a dominant share in 2025, as it has robust investment in pharmaceutical projects, with strong support from advanced clinical trial research facilities. Moreover, the region is stepping into strengthening AI-enhanced predictive analytics, cloud-based Randomization and Trial Supply Management (RTSM) platforms, and blockchain measures. In addition, Health Canada is heavily introducing the first phase of its clinical trials modernization landscape, which spurs expedited review times. Furthermore, regulatory efforts cover the launch of National Priority Vouchers by the US FDA to fast-track progression in high-unmet-need sectors, which impact how sponsors sequence and stock trial supplies.
Asia-Pacific is Projected to Expand Fastest During 2026-2035
Asia-Pacific is projected to grow fastest in the predicted timeframe, supported by broader and more affordable clinical trial conduct and execution of advanced CGT platforms. Day by day, the regional nations are broadly participating in global MRCTs that have expanded the requirement for local depots, import/export assistance, country-specific labeling, and comparator sourcing. Specifically, China implemented revised drug administration regulations that mandate rigorous clinical trial compliance and full-lifecycle traceability. In India, the clinical and commercial supply chain consistently faces susceptibility to upstream key starting materials (KSMs) and advanced intermediates, which forces external sourcing.
Clinical Trial Supplies Market Segmental Glimpse
| Market Segment | Dominant Segment | Key Growth Catalyst |
| By Product Type | Investigational Medicinal Products (IMPs) | Due to a significant role in clinical trial treatment and growth in demand for temperature-sensitive biologicals, cell and gene therapies. |
| By Service Type | Packaging and Labelling | Driven by stringent clinical trial essentials for product identification, blinding, traceability, and regulatory compliance. |
| By Clinical Trial Phase | Phase III | Supported by massive patient populations, entire geographic coverage, and expanded investigational product requirements. |
| By Therapeutic Area | Oncology | Propelled by substantial clinical research activity and continuous development of cancer therapies. |
Developing Transitions
- Expansion of Adaptive Protocols: In 2026, many regulators are using adaptive and master protocol designs, enabling dosing plans, eligibility criteria, and cohort arms to be established mid-study. This needs higher flexibility, as packaging, labeling, and distribution must be adjusted expeditiously based on real-time interim study data.
- Rollout of AI Logistics: Nowadays, predictive AI models are gaining traction to project inventory reduction, control real-time integrity, and front-load risk analysis to mitigate stockouts. Additionally, sponsors are heavily leveraging cloud-based RTSM platforms to ensure end-to-end inventory transparency.
- Progressive Multinational Trials: Specifically, Phase III trials are often operating across >20 nations simultaneously, which is escalating demand for niche logistics providers equipped to manage complex cross-border comparator sourcing and rigorous temperature-controlled delivery.
Future Outlook
The clinical trial supplies market will have immense opportunities and significant development in the coming era. This mainly covers increasing supply chain solutions for Advanced Therapy Medicinal Products (ATMPs), which demand stringent vein-to-vein coordination, ultra-cold or cryogenic storage, and small-batch high-end shipment precision. However, the enforcement of the FDA’s electronic common technical document (eCTD) framework and the EU’s Clinical Trials Information System (CTIS) are highly lowering review cycles and supporting merged regional labeling and packaging centers. Moreover, the future of the market will have a spotlight on patient-centric delivery models that transport investigational medicinal products (IMPs) directly to trial participants’ homes, with maintenance of chain-of-custody and compliance. Alongside this, market firms are pioneering secondary packaging to push patient adherence, sustainable eco-friendly materials, and automated multi-country regulatory labelling.
Segments Covered
By Product Type
- Investigational Medicinal Products (IMPs)
- Comparator Drugs
- Ancillary Supplies
- Medical Devices and Diagnostic Supplies
- Packaging and Labeling Materials
By Service Type
- Manufacturing and Formulation
- Packaging and Labeling
- Storage and Distribution
- Logistics and Transportation
- Supply Planning and Inventory Management
- Returns and Destruction
By Clinical Trial Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By Therapeutic Area
- Oncology
- Cardiovascular Diseases
- Neurological Disorders
- Infectious Diseases
- Immunology and Autoimmune Diseases
- Metabolic Disorders
- Other Therapeutic Areas
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
Empower your strategy with expert insights, purchase this premium research@ https://www.cervicornconsulting.com/buy-now/3061
Ask here for more details@ sales@cervicornconsulting.com