Clinical Trial Supplies Market Size & Forecast 2026 to 2035
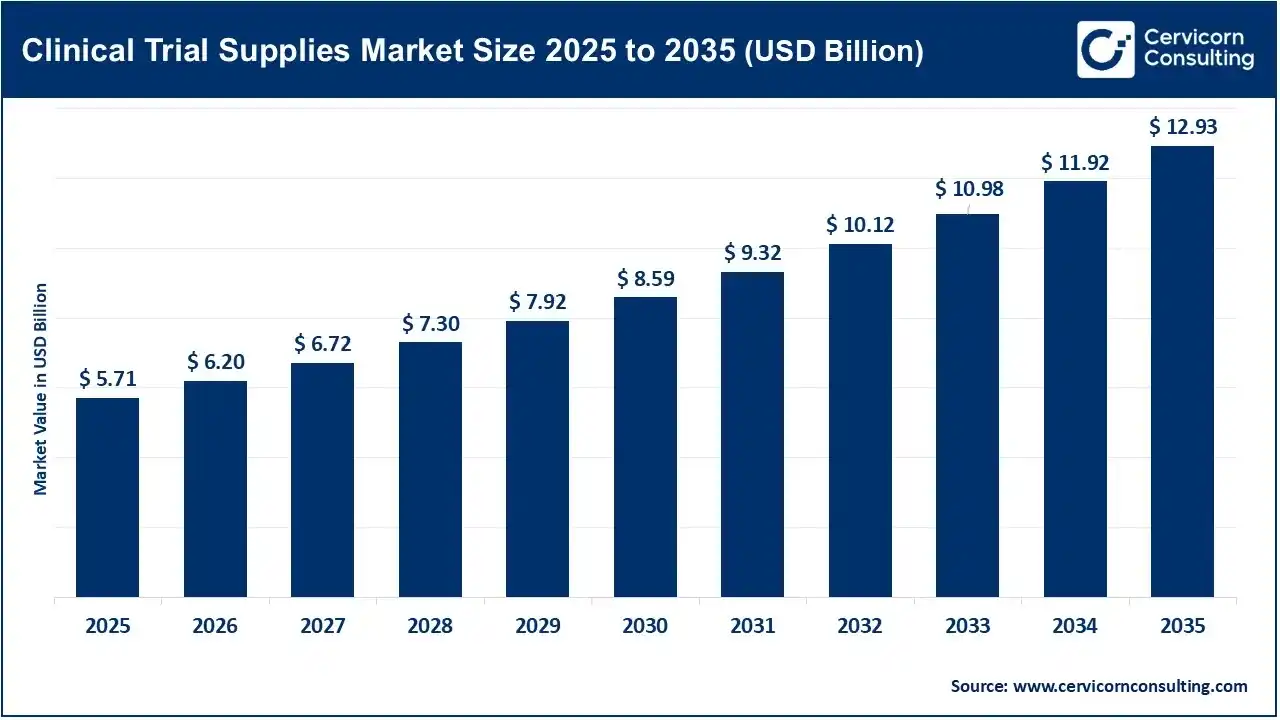
The global clinical trial supplies market size was valued at USD 5.71 billion in 2025 and is expected to reach at USD 12.93 billion by 2035, growing at a CAGR of 8.5% during the forecast period of 2026-2035.
- Base Year Market Size (2025): $5.71 billion
- Current Year Market Size (2026): $6.20 billion
- Estimated Year Market Size (2035): $12.93 billion
- Forecast Period CAGR (2026-2035): 8.5%
Report Highlights
- By region: North America led the market in 2025 with revenue share of 39%, driven by a hub of advanced clinical research infrastructure, massive pharmaceutical investment, and a robust clinical trial ecosystem.
- By product type: Investigational Medicinal Products (IMPs) were dominant in the market in 2025 (revenue share 42%), supported by their major role in clinical trial treatment and assessment.
- By service type: Packaging and labelling dominated the market in 2025 because of rigorous clinical trial requirements for product identification, blinding, traceability, and regulatory compliance.
- By clinical trial phase: Phase III registered dominance in the market in 2025 (revenue share 42%), followed by vast patient populations, comprehensive geographic coverage, and surged investigational product requirements.
- By therapeutic area: Oncology led the market in 2025 (revenue share 28%), propelled by pivotal clinical research activity and consistent development of cancer therapies.
What are the Substantial Advances in the Clinical Trial Supplies Market?
The latest clinical trial supplies highlight the physical materials, experimental products, and tools needed to run a clinical study safely and in compliance with regulatory benchmarks. With a focus on digitalized, patient-centric, and data-driven supply chains, breakthroughs include a higher demand for AI-driven approaches, such as Perceptive eClinical, which is placing machine learning and automated drug forecasting tools to project site demand, reduce product wastage, and mitigate expensive trial delays. More digitalization is also promoting decentralized and hybrid clinical trials to streamline home-use clinical kits and direct-to-patient shipping.
Globally Approved Investigational Medicinal Products (IMPs) Entities in 2025 and 2026
- In 2025, the U.S. Food and Drug Administration's Center for Drug Evaluation and Research (CDER) approved 46 new drugs.
- Across the EU, the European Medicines Agency recommended 104 drugs for marketing authorization, while 38 of these were new active substances in 2025. However, in October and December 2025 alone, 211 new clinical trial applications were submitted per month through the EU Clinical Trials Information System (CTIS).
- South Korea’s Ministry of Food and Drug Safety authenticated 636 Investigational New Drug (IND) approvals in 2025.
- Moreover, UK Research Ethics Committees evaluated 1,028 commercially sponsored research applications in 2025, which include Clinical Trials of Investigational Medicinal Products, or CTIMPs.
As of 2026, ClinicalTrials.gov has tracked approximately 570,000 to 600,000+ total registered clinical studies across the globe, with nearly 58% located outside the U.S.
Where Is the Clinical Trial Supplies Market Shifting in 2026?
- Demonstration of DCTs: This is known as well-known milestone across the market, as leaders are fostering direct-to-patient shipping, remote monitoring, and localized distribution models to uncover standard operational practices.
- Spurring Modernized Infrastructure: Gradually, numerous emerging and major players are experiencing a requirement for ultra-cold chain infrastructure, especially for mRNA entities, cell and gene therapies, and specialized biologics. Hence, to foster such trends, the market is seeking to use integrated supply chain platforms with real-time, sensor-driven temperature monitoring and end-to-end transparency.
- Optimization in Packaging: One of the significant trends, implementation of sustainable workflows, along with a shift towards recyclable, authenticated thermal containers, meeting corporate social responsibility aims and regional regulatory assessments.
Drivers & Restraints Impact
Growth in Consolidated Alliances
- Driver: A surge in need for advanced expertise in the CGT sector.
- Restraint: Increased isolation of standalone cold-chain or local courier vendors.
- Results in: This leads to complete service-centric, multi-year, substantial agreements between companies and combined CROs or CDMOs.
Progression in Adaptive Just-in-Time (JIT) Depots
- Driver: Ongoing adaptive Phase I/II trial models that are looking for dose levels significantly.
- Restraint: A notable surge in spending on drug wastage and product expiration.
- Results in: A prominent transition in packaging and labelling to patients instead of keeping the goal of running the complete process at central production facilities.
Promoting Smart IoT Packaging
- Driver: Gradually rising demand for DTP needs rigorous tracking at patients' homes.
- Restraint: The worldwide accelerating regulatory investigation across product chain-of-custody and temperature surpasses.
- Results in: This will push the expansive adoption of smart sensors, blockchain track-and-trace, along with GPS-monitored smart packaging for legal verification of the drug’s stability during shipping.
Upcoming Events Targeting Clinical Trial Supply in 2027
| Event |
Venue and Date |
Focus on |
| Clinical Trial Supply Forum |
On Feb 9-10, 2027, in Basel, Switzerland |
With a concentrated gathering of global pharma, biotech, and CRO leaders, it has major agendas called management across TSM/IRT, cold-chain, DTP delivery models, developing technologies, etc. |
| Clinical Trial Supply Europe |
On Feb 24-25, 2027, in Barcelona, Spain |
This event has been seeking the presence of key leaders to unveil advanced, cutting-edge solutions and gain the tools to evolve a highly reliable clinical supply chain. |
| ClinChain 2027 |
On Mar 3-4, 2027, in London, UK |
The event has the prominent goal of offering a spectacular experience of the complete CTS, consisting of advanced demand projection, packaging and labelling compliance, innovative cold-chain approaches, eco-friendly measures, etc. |
| Global Clinical Trial & Supply Forum |
On Mar 24-25, 2027, in Boston, USA |
An event is stepping towards the presentation of prospective clinical studies, with their global supply. Also, it has an aim of discovering how AI, digital innovation, patient-focused solutions, sustainability and resilient supply chains will revolutionize its ecosystem. |
Regional Analysis
How did North America Dominate the Market in 2025?
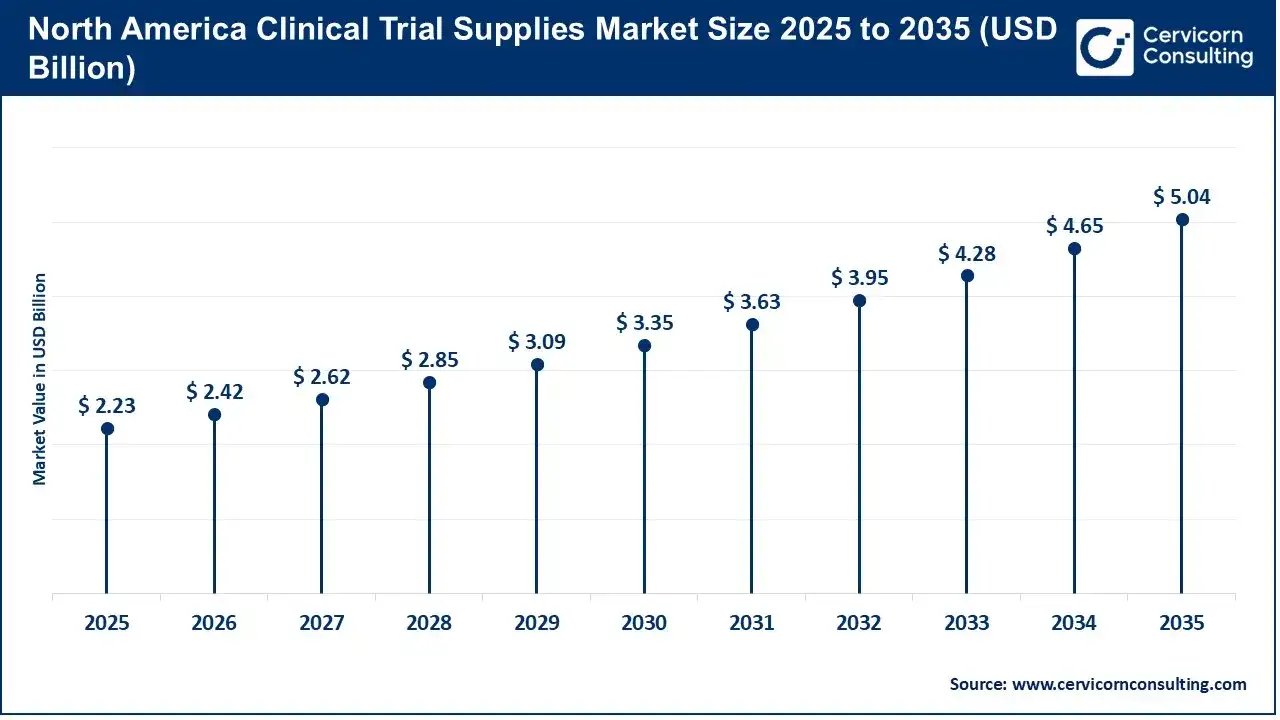
The North America clinical trial supplies market size was valued at USD 2.23 billion in 2025 and is expected to reach at USD 5.04 billion by 2035. In 2025, North America was dominant with a 39% share and was primarily fueled by hubs of well-nurtured clinical research facilities, with ongoing, consistent heavy investment in pharmaceuticals. Day by day, the regional nations are approaching transformations in AI-enabled predictive analytics, cloud-based Randomization and Trial Supply Management (RTSM) platforms, and blockchain solutions. Recently, Canada unveiled that they have conducted nearly 3,100 trials, with key steps in oncology and rare disease therapies to explore tailored interventions for patients.
United States Market Trends
- As a dominant shareholder, the clinical trial supplies market in the U.S. is drastically expanded by continuous clinical trial complexity and massive investments in specialized and highly demanded therapeutics. Most of the evolution in the country has broadened U.S. packaging, labeling, and cold-storage capacity.
Why is the Asia Pacific Considered a Rapidly Growing Region in the Market?
The Asia-Pacific clinical trial supplies market size was estimated at USD 1.37 billion in 2025 and is anticipated to hit USD 3.10 billion by 2035. During 2026-2035, the Asia Pacific is projected to witness the fastest growth, strengthened by a rise in clinical trial capabilities, cost-effectiveness in trial conduction and engaging multi-country studies. As many research studies have shown that India and China will have larger ageing populations, they are widely promoting CGT platforms and groundbreaking therapeutics via modern trials. Recently, CDSCO have declared compressed manufacturing approval timelines from 90 to 45 days, which raises opportunities in advanced studies.
China Market Trends
- In the coming era, China is forecasted to expand at a rapid rate, as it will experience significant growth in elderly people aged 60 and above, roughly 430 million by 2030. This will ultimately lead to the exploration of innovative and latest medicines, especially for autoimmune and oncology cases. For this, nearly 72% of novel clinical trials were reported in China, which comprises Class 1 innovative drugs, i.e. oncology, neuroscience, and metabolic therapies.
Clinical Trial Supplies Market Segmentation Analysis
Product Type Analysis
Investigational Medicinal Products (IMPs): The investigational medicinal products (IMPs) segment held the largest share of 42% in 2025, led by their pivotal role in clinical trial treatment studies and global steps into specialized therapeutics. Expanding demand for a variety of biologics, with an emphasis on lowering supply delays and elevating patient-focused and DTP logistics, fuels the segmental growth.
Medical Devices and Diagnostic Supplies: Among diverse products, the medical devices and diagnostic supplies segment is expected to expand notably, due to transformative regulatory changes, higher demand for remote patient monitoring solutions, continuous glucose monitors, and smart health devices. Regardless of only AI future, many regional pioneers are facing regulatory scrutiny to provide highly strict clinical evidence, especially for moderate-risk Class II devices.
Ancillary Supplies: The ancillary supplies segment is anticipated to grow rapidly during 2026-2035, driven by rising trial complexity, with broader demand for complementary medicines, laboratory materials, and other trial-related consumables. With a huge increase in DTC and hybrid approaches, the market is experiencing a need for specialized cryogenic storage facilities, rigorous chain-of-custody documentation, and protocol-specific ancillary equipment.
Service Type Analysis
Packaging and Labeling: The packaging and labeling segment dominated in the clinical trial supplies market in 2025, supported by global requirements for product identification, blinding, traceability, and regulatory compliance. Additionally, amendments often push accelerated label design advances and rapid re-labelling, coupled with an evolution in serialization, track-and-trace mandates, and easier platforms.
Logistics and Transportation: The logistics and transportation segment is projected to show substantial growth in the coming years, because the massive burden of chronic cases forces accessibility to advanced biological therapeutics, requiring specialised cold-chain solutions. However, globalized and multinational studies also drive specialised cross-border shipping, domestic depot infrastructure, and following regulatory guidelines.
Storage and Distribution: The storage and distribution segment is estimated to expand at a rapid rate during the forecast period, supported by surging decentralized trials, global study growth, and demand for temperature-controlled supply chains. Immersive digital integration covers Interactive Response Technology (IRT) and Randomization and Trial Supply Management (RTSM) systems, with engaging Medidata, Suvoda, and IQVIA to elevate automated inventory management, with less waste & site stockouts.
Clinical Trial Phase Analysis
Phase III: The Phase III segment led the market with 42% in 2025, fueled by vast patient populations, greater geographic coverage, and increased investigational product requirements. Along with its explicit evaluation, this phase facilitates broader and various populations testings, specifically to increase oncology and rare disease prevalence.
Phase IV: Moreover, the Phase IV segment registered a lucrative growth in 2025, as it provides necessary real-world data and safety monitoring after drug approval. Nowadays, the era has moved towards wider utilization of hybrid and decentralized measures, with integrated wearables, digital biomarkers, and remote data recording to trace long-term safety, adherence, and rare side effects in daily patient areas.
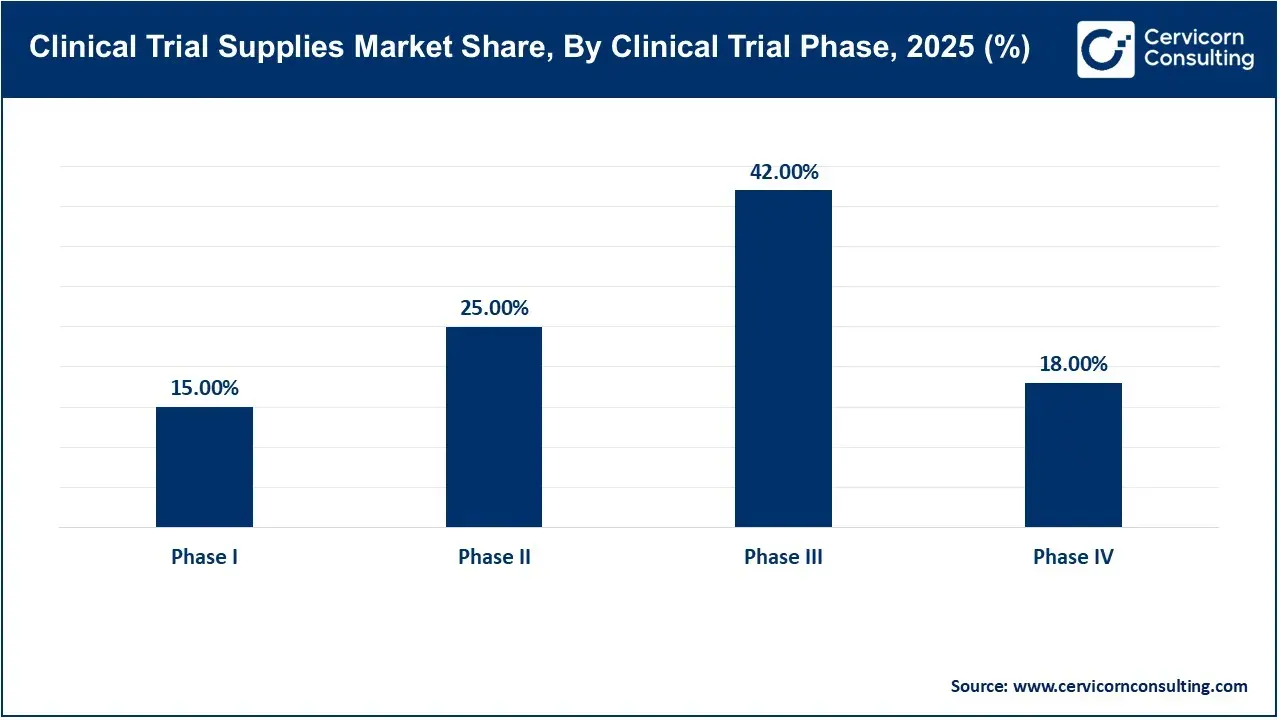
Phase I: The Phase I segment is predicted to grow fastest in the clinical trial supplies market, due to broadening efforts in early-stage drug development and accelerating clinical investigation of innovative therapies. Eventual clinical trial progression is seeking higher adoption of adaptive, perfect, and advanced Phase I designs to receive early proof-of-concept indications, eliminate redundant steps, and foster go/no-go decisions.
Therapeutic Area Analysis
Oncology: The oncology segment captured a dominant share of 28% in 2025, driven by the global burden of cancer cases, with significant clinical research activity and persistent evolution of cancer therapies. Since 2025, the global patient population and healthcare systems have widely demanding personalize interventions, which propels the need for customised investigational product packaging, complex kit assembly, and tighter comparator sourcing.
Immunology and Autoimmune Diseases: Among the many therapeutic areas, the immunology and autoimmune diseases segment is expected to grow notably in the future, supported by the emergence of novelty across cell therapies, diversity in mechanism, and demographic concerns, like dementia. As per certain studies, the worldwide increase in specific inflammations, such as atopic dermatitis, asthma, etc., by 2x to 4x, supports clinical trial innovations and their new supply solutions.
Neurological Disorders: The neurological disorders segment is anticipated to show rapid growth in the market, propelled by advancing research into neurodegenerative diseases, neurological conditions, and novel treatments. According to surveys, by 2030, there will be roughly 75 to 78 million dementia cases and approximately 9 million incidences across the world. This will spur the development of diversified gene therapies, RNA solutions, etc., which need unique modern cold-chain logistics, temperature-controlled buildings, and regulatory compliance.
Government Initiatives
- Collaboration Among NIHR & NHIC: In October 2026, the UK’s National Institute for Health and Care Research and Singapore's National Health Innovation Centre joined to fund later-stage healthcare novelties, covering nearly £500,000 for UK elements and SGD $750,000 for Singapore components to include clinical validation and evidence generation.
- Joint Program by EU and Africa: In 2026, the Global Health EDCTP3 joint program by Europe and Africa made available €147 million for the rollout of collaborative health research and clinical breakthrough projects that connect their institutions.
- DST & Business Finland: Recently, India and Finland introduced the India-Finland Joint Innovation Call 2026 via India's Technology Development Board to provide funding for bilateral technology and clinical-translation projects.
- Global Health Package by Sweden: In 2026, the Swedish government announced a SEK 72 million support package to assist the International Vaccine Institute (IVI) and fund medical technical equipment and supplies distribution.
- World Health Assembly & LMIC Alliances: The 79th World Health Assembly event has showcased that governments from Brazil, Ghana, Sweden, Rwanda, and Viet Nam joined with the IVI and Pasteur Network to impel for equitable clinical trial infrastructure in low- and middle-income countries (LMICs).
Key Companies
Segments Covered
By Product Type
- Investigational Medicinal Products (IMPs)
- Comparator Drugs
- Ancillary Supplies
- Medical Devices and Diagnostic Supplies
- Packaging and Labeling Materials
By Service Type
- Manufacturing and Formulation
- Packaging and Labeling
- Storage and Distribution
- Logistics and Transportation
- Supply Planning and Inventory Management
- Returns and Destruction
By Clinical Trial Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By Therapeutic Area
- Oncology
- Cardiovascular Diseases
- Neurological Disorders
- Infectious Diseases
- Immunology and Autoimmune Diseases
- Metabolic Disorders
- Other Therapeutic Areas
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
